Should You Wait for Interest Rates to Drop? Maybe Not.
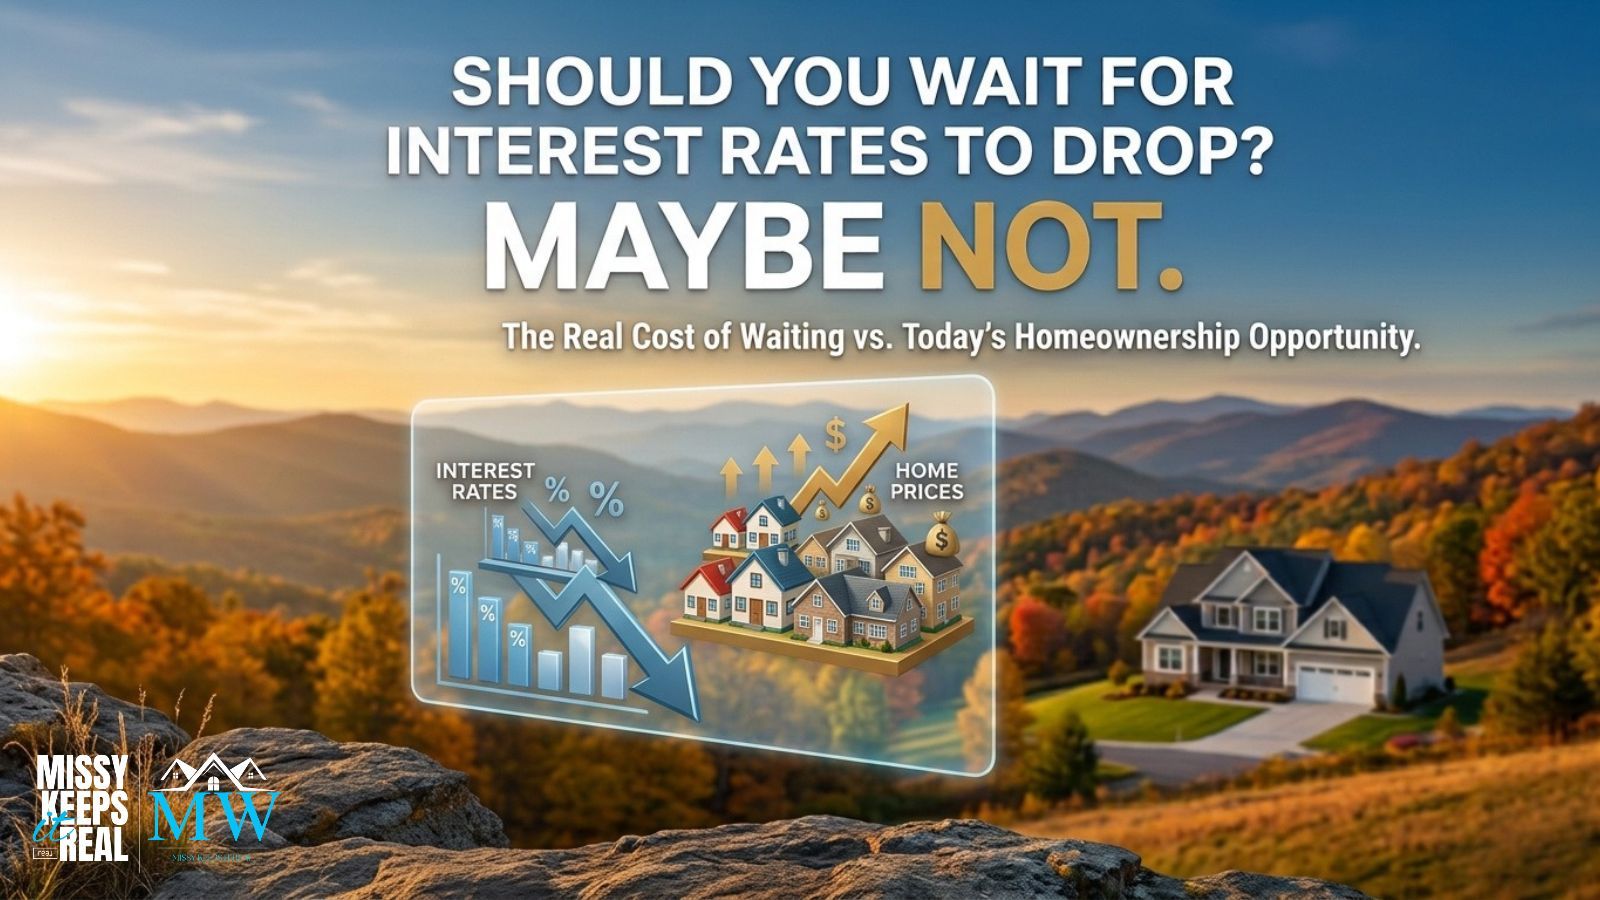
The Rate Dilemma Facing Local Homebuyers
If you’ve been thinking about buying a home in Southern West Virginia or Southwestern Virginia, chances are you’ve been watching mortgage rates closely.
When rates are higher than they were a few years ago, the default thought for many is simple: “I’ll just wait until rates come back down.”
While that seems logical, there is another critical side of the equation every homebuyer in our regional market needs to weigh before hitting pause.
What If Waiting for a Lower Rate Means Paying More for the House?
No one has a crystal ball when it comes to predicting interest rates or regional home values. However, market history shows a consistent pattern: when rates drop, buyers flood back in.
When borrowing becomes cheaper, competition heats up. More buyers competing for the same limited inventory gives sellers maximum leverage—leading to bidding wars, higher purchase prices, and far fewer concessions.
Right now, today’s rate environment creates a unique window of opportunity across Southern WV and SWVA. Because fewer buyers are actively shopping, serious sellers are much more willing to negotiate.
That seller flexibility often converts into concrete savings:
-
💰 Price Adjustments: Negotiating below list price.
-
🏡 Seller-Paid Closing Costs: Credits that directly reduce your out-of-pocket expenses.
-
📉 Rate Buydowns: Seller funds used to secure a 1-to-2% lower interest rate for your first few years.
-
🔧 Repairs & Upgrades: Getting seller concessions for needed maintenance.
Look at the Whole Picture—Not Just the Interest Rate
Consider this real-world regional scenario:
Imagine you find a great home today in Bluefield, Beckley, Abingdon, or Wytheville listed at $250,000. Because competition is light, the seller agrees to cover $5,000 of your closing costs or fund a temporary rate buydown.
Fast forward to a scenario where interest rates fall significantly. Buyers return to the market in droves. That same home could easily command $270,000 or $280,000 in a multiple-offer scenario—with zero seller credits offered.
The key distinction is simple:
-
You can potentially refinance your interest rate later if rates decline.
-
You CANNOT go back and renegotiate a higher purchase price after you buy.
You marry the house, but you date the rate.
Frequently Asked Questions (FAQ)
Q: Should I stretch my budget just to take advantage of seller negotiations now?
A: Absolutely not. The right time to buy is when the monthly payment fits comfortably within your household budget, your personal finances are stable, and you find a property that fits your lifestyle. Never buy solely out of fear or market timing.
Q: How does a seller-funded rate buydown work?
A: A rate buydown uses seller credits paid at closing to lower your mortgage interest rate (typically by 1% to 2%) for the initial 1 to 3 years of your loan, giving you lower initial monthly payments without altering the permanent structure of the mortgage.
Q: What happens if I buy now and rates don't drop for several years?
A: As long as you purchased a home at a price and monthly payment you can afford today, you are safely building home equity in an asset you enjoy—rather than waiting on the sidelines while property values potentially appreciate.
Don't Try to Time the Market. Find the Right Opportunity.
Trying to perfectly time interest rates and home prices is nearly impossible. Instead, focus on finding a property in Southern West Virginia or Southwestern Virginia that checks your essential boxes at a payment you can comfortably afford today.
My goal isn't to pressure you into buying a home. My job is to give you honest, straightforward facts about our local market so you can make the smartest decision for your family.
Ready to Explore Your Options in Southern WV & SWVA?
If you’ve been sitting on the fence because of interest rates, let's have a low-pressure conversation. We can review local inventory, explore what sellers are offering in concessions, and pair you with a trusted lender to run exact payment calculations.
Missy Keeps It Real — Real estate. Honest advice. Zero pressure.
Missy Weddle | Agent | License ID: WVS230302485 & VA-0225267294
Phone: 540-505-7336 | Email: missy@missykeepsitreal.com | Website: missykeepsitreal.com
Brokerage: Real Broker LLC – Melissa “Missy” Weddle
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute formal financial, mortgage, or legal advice. Interest rates, loan terms, and market conditions vary by location and personal qualifications. Always consult with a licensed real estate professional and qualified mortgage lender regarding your specific situation.
GET MORE INFORMATION